Transitioning
Into Residency

Residency is the first time in years that money moves toward you rather than away. It is also when relocation, licensing fees and the end of your interest-only period tend to arrive at once. The transition is manageable, but not if the first time you look at it is the week you start.

Gurjeet S. Rai CFP

Gurjeet S. Rai CFP

A young physician in medical uniform carrying a case

Your first residency paycheque is smaller than you expect. Gross salary and take-home pay diverge sharply once deductions come out. Build the new plan against the number that lands in your account, not the number in the offer letter.

Start from an actual pay statement rather than an annual figure. Between federal and provincial tax, CPP, EI, pension contributions and association dues, the gap between gross and net is wider than most students anticipate.

Then add the costs that appear only at this transition: relocation, a new lease and deposit, licensing and registration, exam fees, and often a car in a city with less transit than the one you trained in.

The instinct after years of borrowing is to treat a first salary as relief and let spending expand to meet it. That is understandable, and it is the most expensive habit available to you at this point.

Holding spending near student levels for the first few months, while you learn what the job actually costs, buys you information and a buffer at the same time.
The First
Six Months

A workable order for the transition. None of it takes long, but the sequence matters more than the speed.

Step 1
A student sitting at a table writing notes on paper
Rebuild the Budget

Take one real pay statement and work out your true monthly net. Set rent, transport, food, debt payments and professional costs against it. Everything else on this page depends on knowing that number first.

How this works
1.

Know what actually lands before you commit to anything.

Step 2
A student writing notes on paper at a desk
Handle the Handover

Your line of credit changes when training ends. The interest-only period closes, the rate may move and the limit is often reduced. Confirm the date and the new payment with your lender rather than waiting to be told.

How this works
2.

The terms change. Know the date and the new payment.

Step 3
A physician in a white coat standing in a clinical setting
Review Your Protection

Your income, your occupation class and the options available to you all change at this point. Coverage arranged as a student is worth re-reading now, alongside whatever you hold through an association or your program.

How this works
3.

New income, new obligations, coverage worth re-reading.

First-Year Priorities

1.

Eight things worth doing before your first year is over.
None of them are urgent in week one, and all of them are easier to do while the transition is still fresh than to reconstruct a year later.

Residents who handle this well are rarely the ones who earn most. They are the ones who looked at the numbers early and made a small number of deliberate decisions.

In Your First Year:

Read One Pay Statement Properly

Gross, every deduction, and the net figure. Everything else on this list depends on knowing that number rather than estimating it.

Confirm Your Credit Terms

When the interest-only period ends, what the rate becomes, whether the limit is reduced, and what the new minimum payment will be.

Start the Emergency Fund

You now have income to build one from. Residency is the first point where an accessible reserve becomes realistic rather than theoretical.

Review Disability Coverage

Your income, occupation class and available options all change here. Read what you already hold before deciding whether anything else is needed.

Budget for the Move Itself

Relocation, deposit, furnishing and travel between sites are front-loaded into the first months, often before your second paycheque.

Track Professional Expenses

Licensing, exams, dues and equipment. Some may be deductible depending on your circumstances, so keep the records from the first month.

Go Slow on Lifestyle

A newer car and a larger apartment are the two decisions hardest to reverse. Both are easier to make well after six months of real data.

Set a Six-Month Review

Put a date in the calendar now. Revisit the budget against what the year actually cost, and adjust rather than assume.

Planning the
Move?

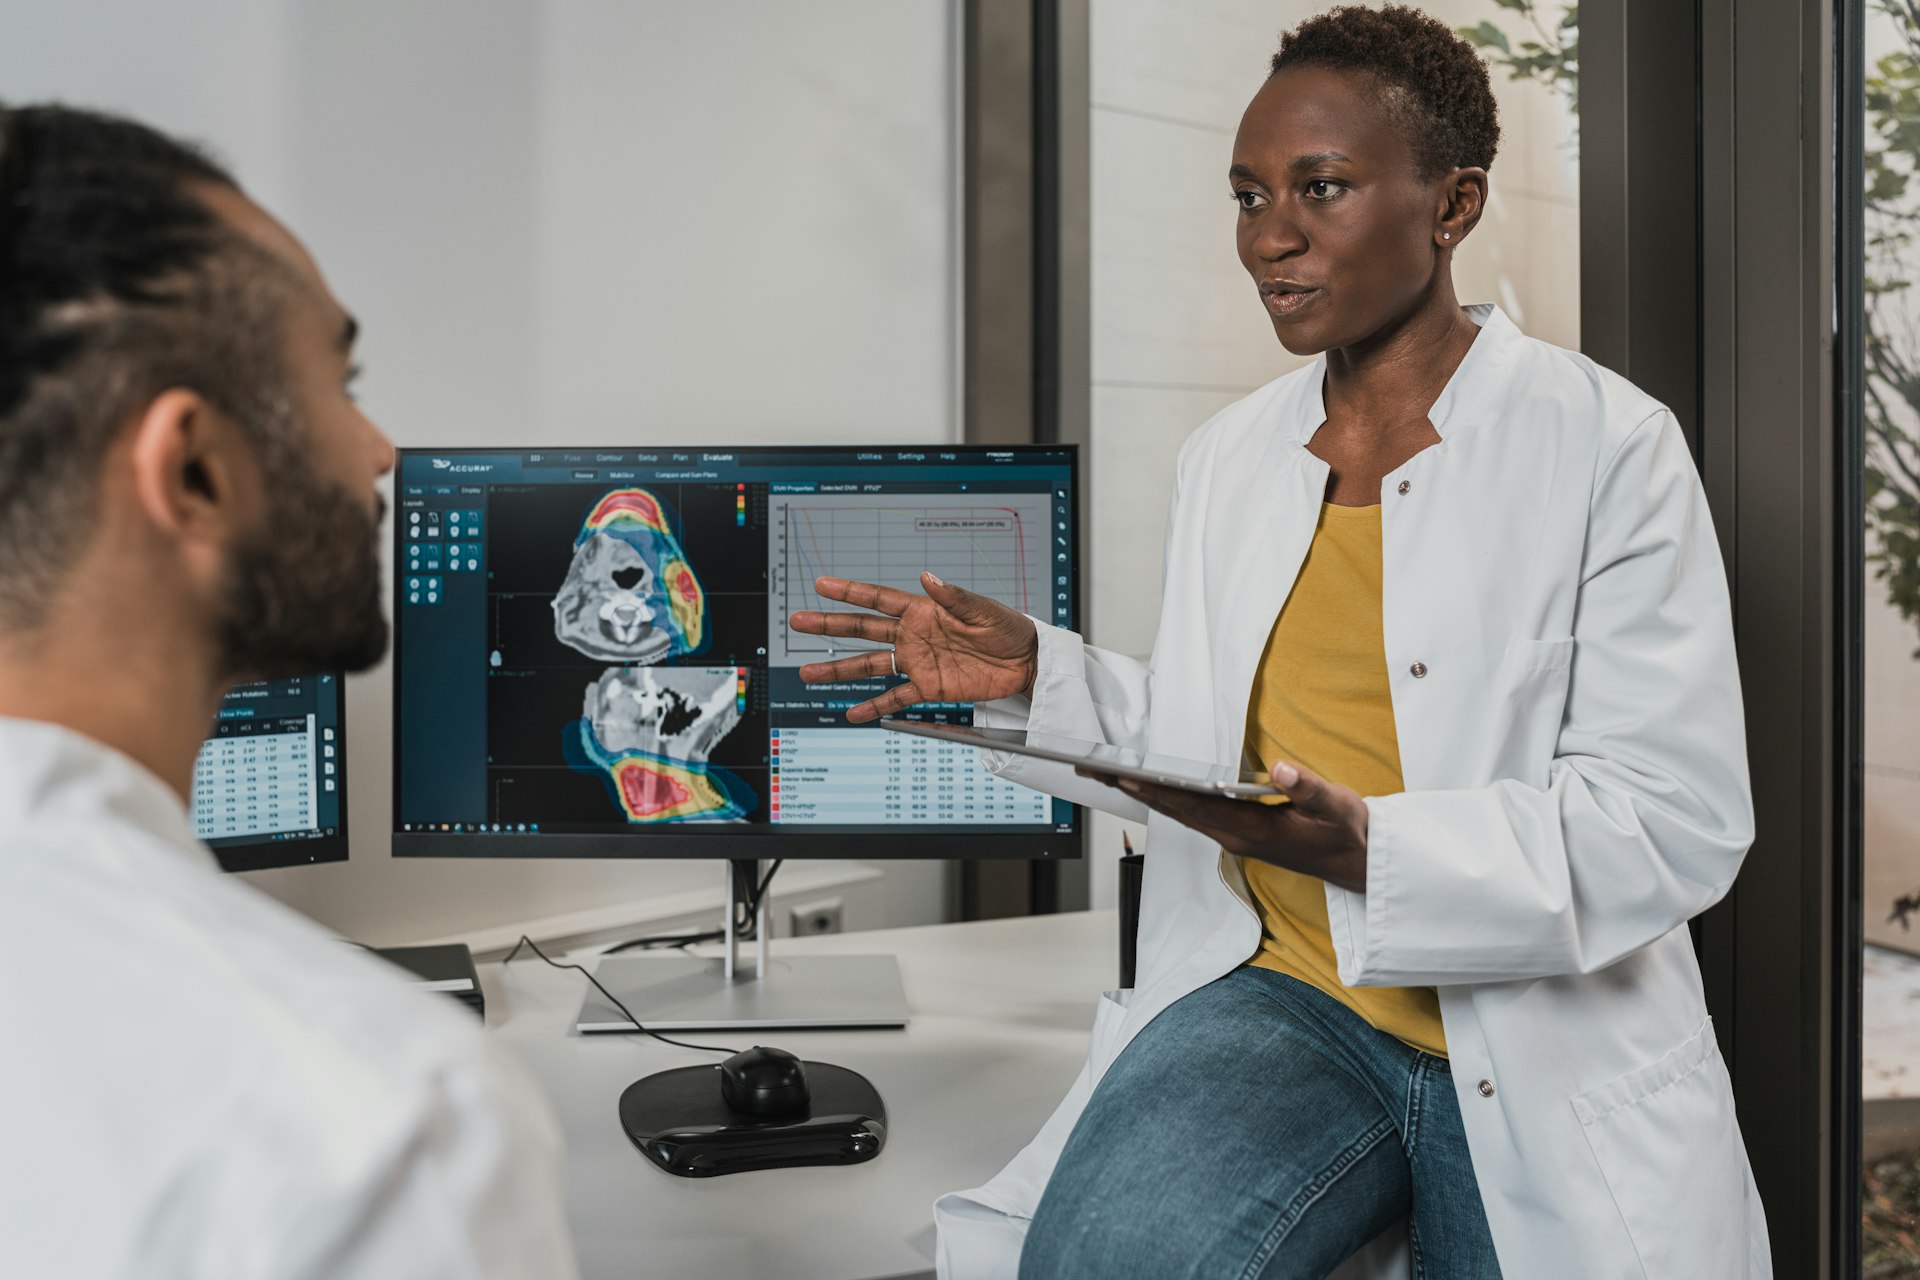
Two clinicians discussing medical imaging on a monitor
If residency is approaching and you want to work through the cash flow, the debt handover and your coverage before it starts, that is the conversation to have now rather than in month three.

Optional supporting paragraph. Use it when the lead statement needs practical detail underneath — how the approach works, what it covers, or what happens next.