Managing a
Line of Credit

Access to credit and affordability are not the same thing. A professional student line of credit is one of the few borrowing arrangements offered on the strength of a career you have not started yet. That is a genuine advantage. It is also why the approved limit tends to be considerably larger than what your training actually costs.

Borrowing

Borrowing

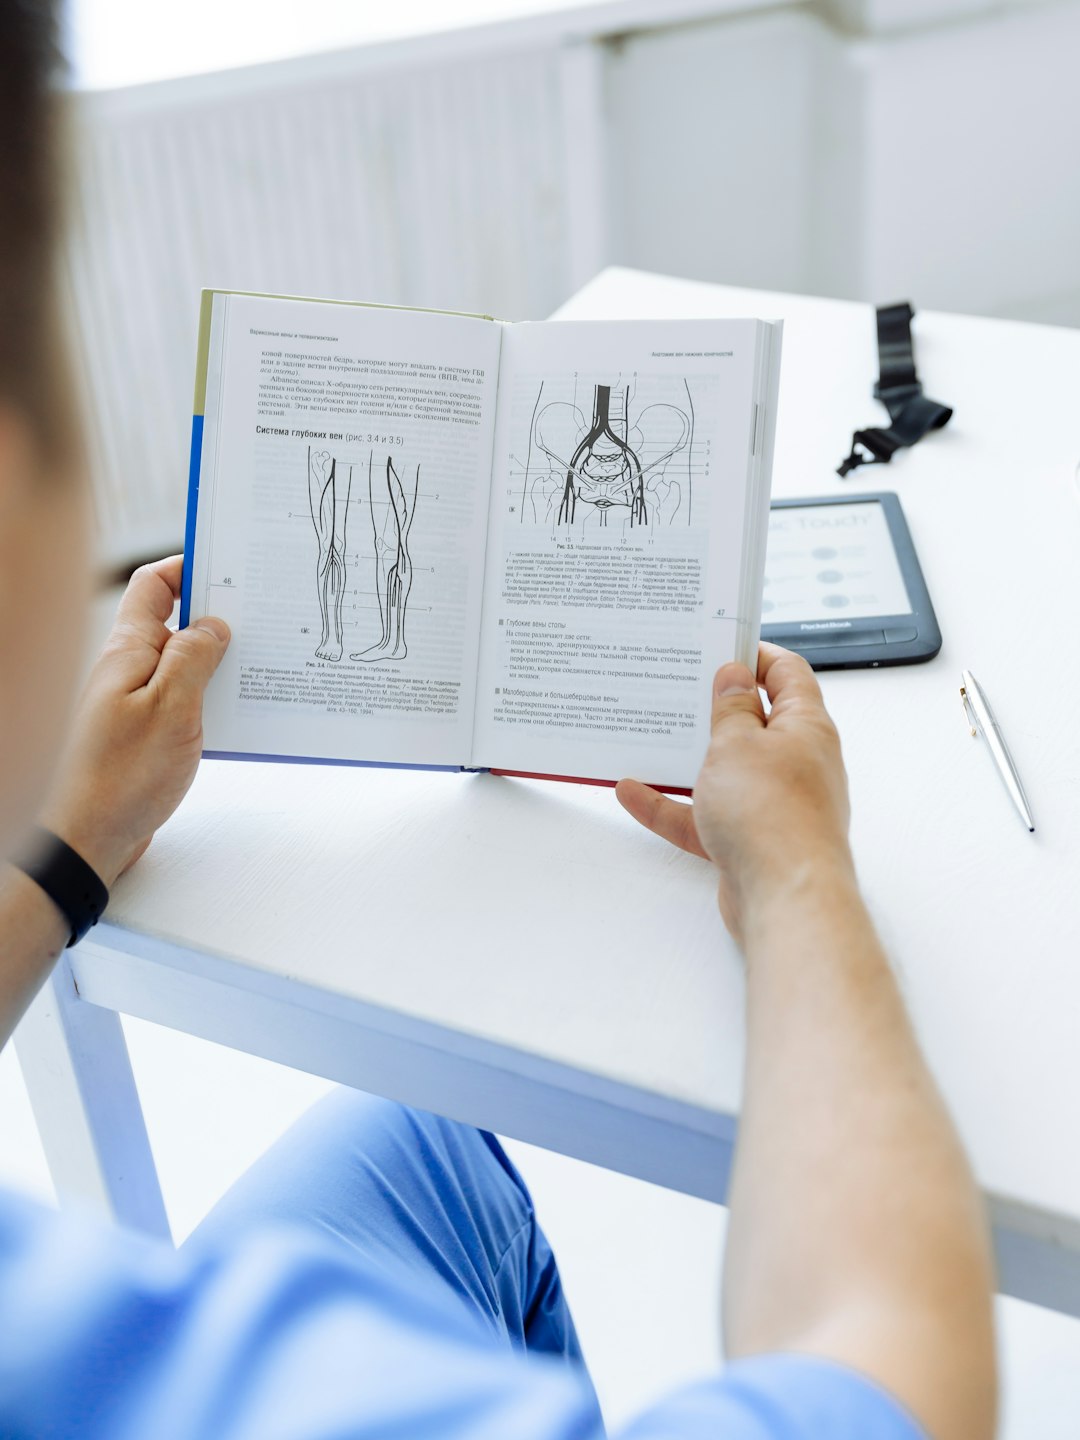
A student sitting at a desk reading a book

Start from what medical school actually costs you. Not from what you have been approved for. Those two numbers are rarely close, and the gap between them is where most avoidable debt gets created.

Build the estimate from things you can count. Tuition and fees for each year of your program. Housing, including the months you will spend on rotation somewhere else. Transport, food, phone, insurance.

Then add the professional costs that are easy to overlook: equipment, exam registrations, licensing, and the travel that comes with electives and interviews. These are the items that turn a comfortable year into a tight one.

Set that total against everything coming in. Savings, family contributions, government student aid, summer income, bursaries and scholarships. What remains is your genuine borrowing need for the year.

The number will not be tidy and it will change. Estimate it anyway. A rough figure you revisit each term is far more useful than an approved limit you never examine, and most students find the exercise reassuring rather than alarming.

Before You Draw

2.

A borrowing plan takes an afternoon and saves years of guessing.
These are the things worth settling before your first withdrawal rather than after it, when the balance is already built.

Worth Settling First:

Your Annual Need

The real cost of one academic year, net of every source of income. Not the four year total, which is too abstract to manage against.

Your Interest Rate

Know whether it is fixed or variable, what it is tied to, and what a rate change would do to the balance you expect to finish training with.

The Interest-Only Period

Most professional lines of credit ask only for interest during training. Know the date that ends and what the payment becomes when it does.

What You Will Finance

Decide in advance which categories you are willing to borrow for. Tuition and rent are straightforward. A holiday is a decision worth making deliberately.

Your Other Funding

Provincial aid, bursaries, scholarships and summer income all reduce what you need to draw. Confirm the amounts and timing before assuming them.

A Review Rhythm

Once a term is enough. Check the balance, the interest accrued, and whether your spending has drifted from what you planned.

The Residency Handover

Terms usually change when training ends. Know what happens to your rate, your limit and your repayment schedule before that date arrives.

If Plans Change

A leave of absence, a research year or a change of program all affect eligibility and terms. Ask what happens rather than assuming continuity.

Limit Versus
Budget

The single most useful distinction on this page. These are two different numbers, and only one of them should drive what you spend.

Spending to the Limit
A student writing notes on paper at a desk
Your Credit Limit

Set by the lender, based on your program and your expected future income. It does not move when your circumstances do, it carries no judgement about what you should spend, and it was never intended as a target. Treated as a budget, it quietly becomes one.

Borrowing to the Plan
A student sitting at a table writing notes on paper
Your Actual Budget

Built from what this year genuinely costs you, net of income. It moves when your circumstances move, it is yours to revise, and it is the number that determines the debt you carry into residency and the years after it.

Both numbers are real. Only one of them reflects your situation. The distinction matters most for discretionary spending, which is exactly where an approved limit tends to get treated as permission.

Protect What Comes Next.

Protect What Comes Next.

What Happens to Your Medical School Debt If Something Happens to You?

A medical education can come with a significant financial commitment.

For some students, a professional line of credit can reach several hundred thousand dollars by the time they complete medical school and residency. Most physicians expect their future income to allow them to repay that debt over time.

But there is another question worth considering:

What happens to that financial obligation if you are not there to repay it?

The answer depends on how your borrowing is structured, whether anyone else has guaranteed the debt, and what financial protection you already have in place.

Who Is Responsible
for the Debt?

Our family does not automatically become responsible for your medical school debt simply because they are related to you. However, the situation may be different if a parent, spouse or another person has signed as a co-borrower, co-signer or guarantor. Before considering whether additional protection is needed, understand exactly how your line of credit is structured and whether anyone else has a financial obligation connected to it.
Who Could
Be Affected?

The impact of medical school debt depends on how the borrowing is structured and whether anyone else has a legal obligation connected to it.
Three common situations are worth understanding.

1
A clinician in a white coat with arms folded
Only You Borrowed
1.

If the line of credit is solely in your name, the outstanding balance would generally be dealt with through your estate.

Whether additional protection is needed will depend on your assets, liabilities and overall financial circumstances

2
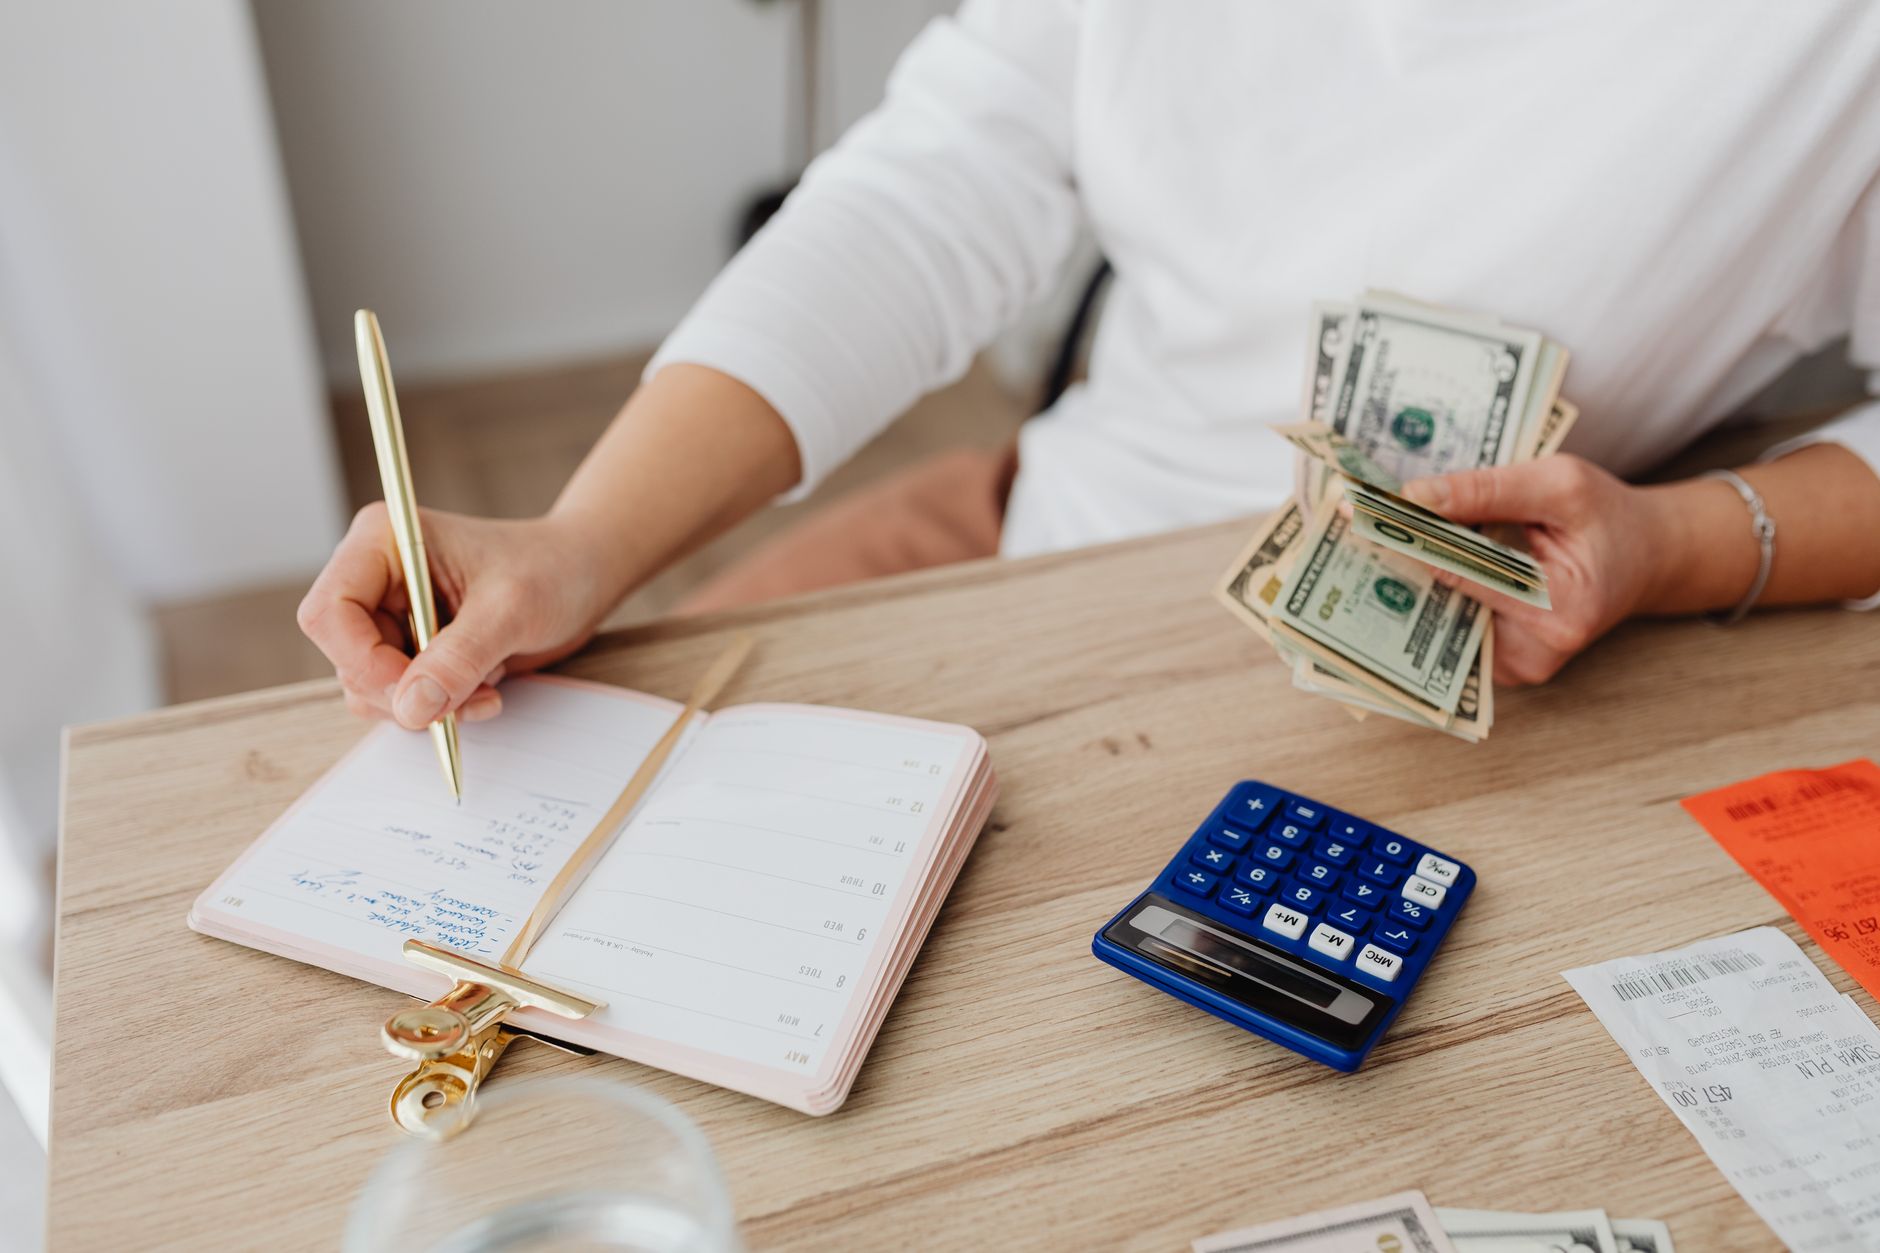
A person writing in a planner while using a calculator
Someone Guaranteed It
2.

If a parent, spouse or another person has co-signed or guaranteed the borrowing, they may have responsibility for the debt under the lending agreement.

This is where understanding the terms of the line of credit becomes especially important.

3
Two people reviewing and signing an insurance policy document at a desk
You Already Have Coverage
3.

You may already have some protection through a lender, school, association, employer or personal policy.

The key is understanding how much coverage you have, how long it lasts, who receives the benefit and whether it changes as your circumstances change.

When Does Life Coverage Start Becoming Relevant?

1.

There is no specific year of medical school when every student needs life insurance. It becomes worth reviewing when your financial responsibilities begin to change and other people could be affected by those responsibilities.

Key Components Include:

Your debt has grown significantly

As your line of credit balance increases, it becomes more important to understand what would happen to that obligation if you were no longer able to repay it.

Someone else is financially connected

If a parent, spouse or another person has guaranteed or co-signed your borrowing, protecting that obligation may become more relevant.

Your personal life changes

A spouse, partner, children or a new home can create financial responsibilities that extend beyond your medical school debt.

You are entering residency or practice

As you begin earning income and building assets, your financial picture becomes more complex and your protection needs may change with it.

For many physicians, this conversation becomes more relevant closer to graduation, during residency or as they transition into practice.

The goal is not to purchase coverage simply because you have debt. It is to recognize when your financial responsibilities have changed enough to warrant a review.

Three Questions
To Ask yourself

Before deciding whether any additional protection is worth considering, start with a few basic questions about your debt and your financial situation.

Step 1
A student concentrating on notes at a desk
What Do I Owe, and For How Long?

Look at your current line of credit balance, government student loans and any other significant financial obligations.

Also consider how long you expect those obligations to remain substantial as you move through residency and into practice.

What Do I Owe, and For How Long?
1.

Look at your current line of credit balance, government student loans and any other significant financial obligations.

Also consider how long you expect those obligations to remain substantial as you move through residency and into practice.

Step 2
Is Anyone Else Responsible?

Confirm whether a parent, spouse or another person has signed as a guarantor, co-signer or co-borrower.

This is one of the most important details in determining whether someone else could be financially affected.

Is Anyone Else Responsible?
2.

Confirm whether a parent, spouse or another person has signed as a guarantor, co-signer or co-borrower.

This is one of the most important details in determining whether someone else could be financially affected.

Step 3
What Protection Do I Already Have?

Review any coverage connected to your bank, school, association, employer or an existing personal policy.

Make sure you understand how much coverage exists, who receives the benefit and how long the coverage lasts.

What Protection Do I Already Have?
3.

Review any coverage connected to your bank, school, association, employer or an existing personal policy.

Make sure you understand how much coverage exists, who receives the benefit and how long the coverage lasts.

Different Ways the
Risk Can Be Addressed

Depending on your circumstances, there may be different ways to protect against the financial impact of outstanding debt.

The right approach depends on how your borrowing is structured, what protection you already have and who could be affected.

Lender-Related Protection
Protection Through Your Lender

Designed around the debt
Coverage may be connected directly to a loan or line of credit.

Terms are set by the lender
Eligibility, coverage amounts and how benefits are paid depend on the specific product.

May change with the loan
Coverage can sometimes be tied to the outstanding balance or to your relationship with the financial institution.

Personally Owned Life Coverage
Personally Owned Coverage

Broader financial protection
Coverage can be used to address debt as well as other financial responsibilities.

You control the policy
The policy is generally owned independently of the lender.

Can continue beyond the debt
Coverage may remain in place even as your debt decreases or your financial circumstances change.

The goal is not to choose the most coverage. It is to choose what fits your actual financial risk.

Planning for What’s Next

Two doctors in white coats walking through a hospital courtyard

Your Financial Needs Will Change

Your medical line of credit is only one part of your financial life.

During medical school, the priority may simply be understanding your debt and whether anyone else is financially connected to it.

As you move into residency, your situation can change quickly. Income begins, debt repayment becomes more relevant, and you may start taking on new responsibilities such as housing, a spouse or partner, savings and investing.

Once you enter practice, your financial planning may expand further to include incorporation, tax planning, family protection and longer-term wealth building.

Your financial strategy should evolve as your medical career does.

Residency

A young physician in medical uniform carrying a case

Your borrowing plan should change when your income does. Residency brings employment income and a very different cash flow, but the balance you built during medical school does not reset with it.

Repayment terms on most professional lines of credit shift once training ends. The interest-only period closes, the rate may change, and the available limit is often reduced.

Knowing the date and the numbers ahead of time turns a surprise into a plan you have already made.

Residency is also when competing demands arrive together: moving costs, licensing fees, exam registrations, and for many students the first serious look at disability coverage.

A borrowing plan that already accounts for the handover leaves room for those without another draw on the line.

Borrowing With
a Plan?

A physician in a white coat standing in a clinical setting
If you are trying to work out how much to draw, or what your line of credit will look like once residency begins, that is worth talking through.

Optional supporting paragraph. Use it when the lead statement needs practical detail underneath — how the approach works, what it covers, or what happens next.